A complete toolbox
A considered financial life, built with every tool at hand.
For healthcare professionals, families, and business owners who want a plan matched to their life — not a single product pitched to fit it.
The toolbox
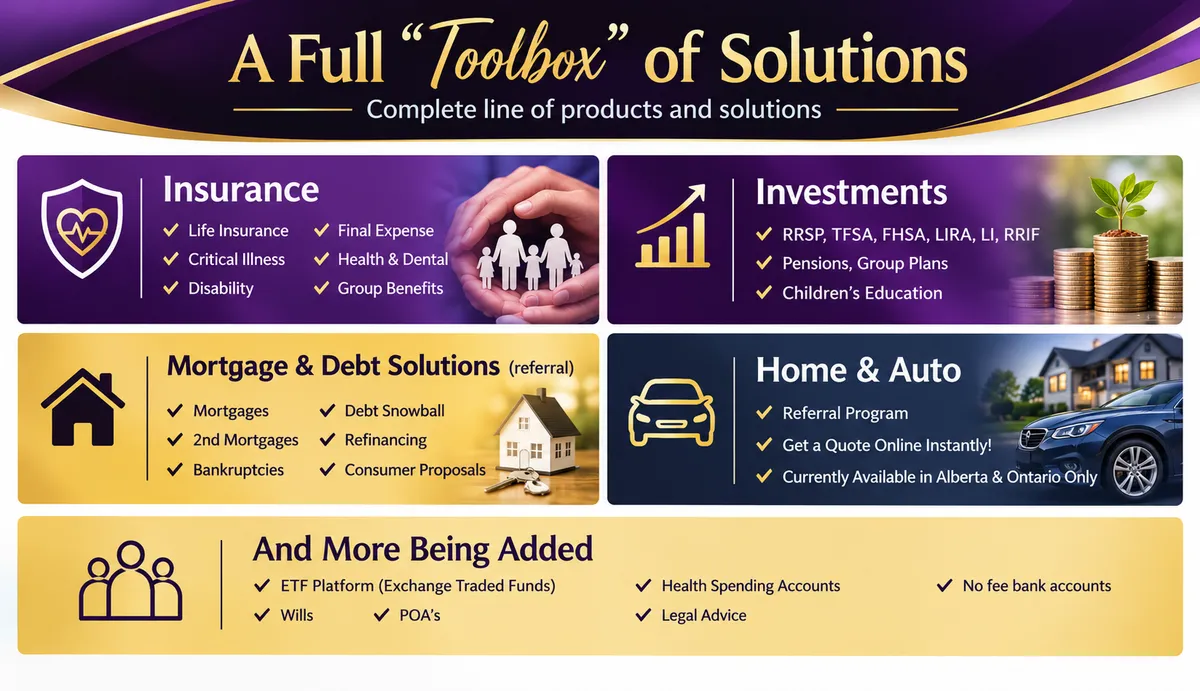
Four disciplines. One plan.
Each conversation starts with your life, then draws on whichever of these your plan actually needs.
I- Protection
Coverage that holds if income, health, or life takes an unexpected turn.
Life · final expense · critical illness · disability · health & dental · group benefits
II- Investments
Structured growth across the accounts already available to you.
RRSP · TFSA · FHSA · LIRA · LIF · RRIF · pensions · group plans · education savings
III - Mortgage & Debt
Referral partnerships for the debt side of the plan, handled with the same care.
Mortgages · second mortgages · refinancing · debt strategy · bankruptcy & proposal referrals
IV- Home & Auto
Quoted instantly where you're covered, referred where you're not.
Referral program · instant online quotes · currently Ontario & Alberta
Life insurance, explained simply
The basics in plain words: what it is, the two main types, and what critical illness cover adds.
What is life insurance?
You pay a small amount every month. If you pass away, the insurance company pays a big sum of money to the people you choose, like your family. It helps them cover the bills, the home and school costs when your paycheque is gone.
Term insurance
Think of renting. It covers you for a set time, like 10, 20 or 30 years. If that time ends and you’re still here, the cover ends too.
It costs the least and has no savings part.
Permanent insurance
Think of owning. It covers you for your whole life as long as you pay. Part of what you pay builds cash value, a savings pot you can borrow from.
It costs more than term.
Whole life
The steady kind. Your price is set and your savings pot grows by a promised amount.
Universal life
The flexible kind. You can change how much you pay, and the savings pot grows with investments, so it can go up or down.
What is critical illness cover?
It pays you cash while you’re still alive if you get a serious illness on the policy’s list, like cancer, a heart attack or a stroke. You spend it however you need, on bills, treatment or time off work to recover.
Estimate your cover
Tell us who’s being covered and what you can spend each month. We’ll show how much cover that budget buys with term, whole life and universal life, with and without critical illness.
Insurers usually price on sex, so that sets the rate. Gender is kept for your summary only.
What changes your result
For term, a longer term costs more. For permanent plans, paying over fewer years costs more each month.
Three stories
See how the same choices play out at 18, 30 and 65. Tap a story to open it.
Maya, 18: locking in a low price
Maya just started university. Her parents co-signed her student loan, so she wants them protected if something happens. She’s young, so insurance is at its cheapest.
- Term life: up to $1,840,000 of cover
- Term with critical illness: $445,000 of life cover plus $111,250 if she gets seriously ill
- Whole life: $145,000 of cover that also builds cash value
Her pick: term. She gets the most cover for her budget, and the low price stays fixed for 30 years.
Daniel, 30: protecting a new family
Daniel just became a dad and bought his first home. If he couldn’t work, for any reason, his family would struggle to pay the mortgage until their child is grown.
- Term life: up to $2,455,000 of cover
- Term with critical illness: $825,000 of life cover plus $206,250 if he gets seriously ill
- Universal life: $340,000 of cover with a flexible savings pot
His pick: term with critical illness. It covers the years of the mortgage and gives him money to recover if he gets sick.
Rosa, 65: leaving a gift behind
Rosa is about to retire. She wants to cover her final costs and leave something for her grandchildren, without paying premiums for the rest of her life.
- 10-year term: up to $750,000, but it ends at age 75
- Whole life, paid in 10 years: $75,000 that lasts for life
- Whole life with critical illness: $50,000 of life cover plus $12,500 if she gets seriously ill
Her pick: whole life. It costs more per dollar of cover, but it never expires and she’s done paying at 75.
These stories use the estimator’s rough numbers. Real prices depend on health and the insurer.
These are rough estimates for a healthy non-smoker, built from simplified rate curves. They are not quotes. Real premiums depend on your health, smoking status, insurer and underwriting. Speak with a licensed advisor before you buy.
Plan · Protect · Build · Live
Why clients choose this practice
The complete toolbox, not one product line
Guidance shaped by a caregiving background
Carrier-verified, transparent recommendations
Standing behind Wealth
Who's This Perfect For
A smarter financial strategy starts with understanding where your money is going—and where you want it to take you.
Healthcare Professionals
Protect the income you work hard for.
Build a financial strategy around shift work, income protection, benefits, retirement, and family security.
Business Owners
Keep more of what you earn.
Explore strategies for protection, benefits, retirement, debt management, and long-term business and family planning.
Young Professionals
Build your financial foundation early.
Create a savings, protection, and investment strategy designed around your goals—not just your next paycheck.
Families
Protect today. Prepare for tomorrow.
Plan for life insurance, education savings, retirement, unexpected expenses, and the people who depend on you.
🇨🇦🇺🇸 Available to Eligible Clients
Serving eligible clients in Canada and the United States.
Financial solutions are based on your individual situation, goals, and eligibility.
Aspiring Entrepreneurs
Turn your ambition into a financial plan.
Learn how to prepare financially for entrepreneurship while building protection and long-term wealth.
Career & Income Seekers
Create more options for your future.
For people looking to explore additional income opportunities while developing financial knowledge and entrepreneurial skills.
Wealth Builders
Make your money work with purpose.
Identify opportunities to improve cash flow, strengthen savings, protect assets, and work toward your long-term financial goals.
Future-Focused Doers
People who rather work for Their future than depend on other people or wait for an opportunity they cannot perceive
Frequently Asked Questions
What is life insurance, and how does it work?
Life insurance is a contract between you and an insurance company, where you pay regular premiums, and in return, the company provides a lump-sum payment, known as a death benefit, to your beneficiaries upon your passing. This payment can be used to cover expenses such as funeral costs, mortgage payments, and other financial needs.
What types of life insurance policies are available?
There are primarily two types of life insurance: Term life insurance, which provides coverage for a specified period (e.g., 10, 20, or 30 years), and Whole life insurance, which offers lifelong coverage and includes a savings component that builds cash value over time.
How much life insurance coverage do I need?
The amount of life insurance you need depends on your financial obligations, such as mortgage payments, outstanding debts, future education costs, and your family's living expenses. A general rule of thumb is to have coverage that is 5-10 times your annual income, but this can vary based on individual circumstances.
Can I change my life insurance policy after purchasing it?
Yes, many life insurance policies offer flexibility. You may be able to adjust your coverage amount, convert a term policy to a whole life policy, or add riders for additional benefits. It's important to review your policy regularly and discuss any changes with your insurance advisor to ensure it continues to meet your needs.
Testimonials
"I highly recommend her"
Maydelyn made the insurance process easy to understand. Friendly, knowledgeable, and always ready to tackle our questions. She is highly committed to her profession and has an outstanding work ethic. Her moral standards are of the highest caliber. I highly recommend her to anyone looking for an insurance agency that puts customers first.
I would like to take this opportunity to thank her excellent service. I enjoyed dealing with her for the yearly statement reviews of my family's Ivari Life Insurance.
Rodel P.
"Amazing, Kind, & Hardworking"
I have known Maydelyn since 2017 and she has been an amazing, kind, and hard working individual. I have consulted her on most of my insurance needs and she has constantly reminded me over the years to have a more secure insurance for any untoward events. When I finally freed up some budget for it I immediately contacted her to be my agent because I know she will be able to provide me with the best service I can get. I am very satisfied with the policy I have right now and I do not see myself changing it in the near future. Maydelyn is one of the best persons I know to do the job right and fast and I can confidently place my trust and safety to her.
John Mendoza
Sarah M
Book your ApPOINTMENT TODAY
Reserve your time
Let's build your plan.
Book a private 20-minute assessment, or leave your details and I'll reach out within one business day.
Contact
Site: secure.maylifecarem8.com
Hours
Mon – Sat 9:00am – 8:00pm
Sunday – CLOSED